Raw Material Prices Remain High; Cost Support Strengthens at the Margin
In October, the prices of core raw materials for polyester resins generally showed an oscillating upward trend, and the supporting effect of the cost side on the industry strengthened significantly compared with September. As of October 23, the current average price of PTA was 7,120 yuan/ton, up 3.98% month-on-month, making it the largest source of cost pressure for polyester resin factories. Although neopentyl glycol (NPG) fell after the National Day holiday, its price center remained high, with the market average price rising 1.4% month-on-month. The price of isophthalic acid (IPA) increased 1.4% compared with last month amid rising costs and concentrated plant maintenance. Trimethylolpropane (TMP) first rose and then fell, with an overall increase of only 0.2%; adipic acid and trimellitic anhydride showed slightly stronger gains, rising 7.84% and 9.16% respectively. Affected by the transmission of raw material prices, the production cost of polyester resins increased noticeably.
2026 Price Trend Chart of Major Raw Materials for Polyester Resins
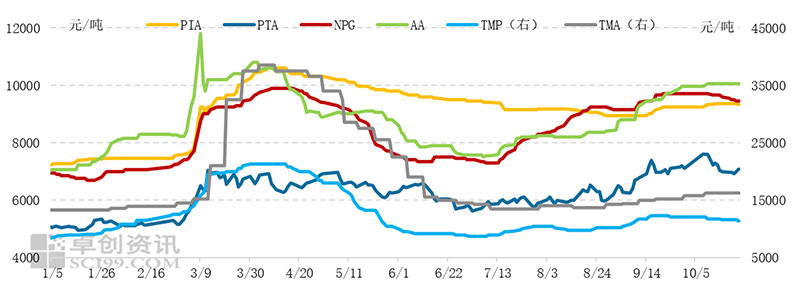
Data source: Sublime China Information (SCI)
Supply-Demand Contradiction Becomes Prominent; Polyester Continues Destocking
In October, although the overall operating rate of China's polyester resin industry was better than that in September, some factories suspended production temporarily due to the National Day holiday, and some even did not resume operations after the holiday. However, most factories still had finished product inventories and maintained strong order-taking capacity, with the industry continuing to focus on destocking. Downstream demand ushhered in a traditional peak-season recovery. The powder coating sector benefited from the autumn and winter construction window, with orders for aluminum profiles, construction machinery, and home appliance coatings growing somewhat; however, willingness to accept high prices remained insufficient, cost transmission resistance was significant, and ordering was extremely cautious, putting the polyester resin industry in the awkward position of "no orders if prices rise, losses if prices don't rise."
Multiple Factors Combined: Polyester Resin Industry Under Pressure in Q4
Overall, in the fourth quarter, driven by both the marginal cost support from raw materials and the demand recovery in the traditional downstream peak season, the overall market resilience of the polyester resin industry has strengthened significantly. Current industry pressure mainly stems from high costs coupled with insufficient downstream demand recovery. If crude oil prices remain high, raw materials may still find support, and polyester resin prices will likely remain relatively strong. Once oil prices fall, however, given the industry's continued destocking and insufficient raw material inventories across downstream segments, the decline may still be limited even if prices drop.